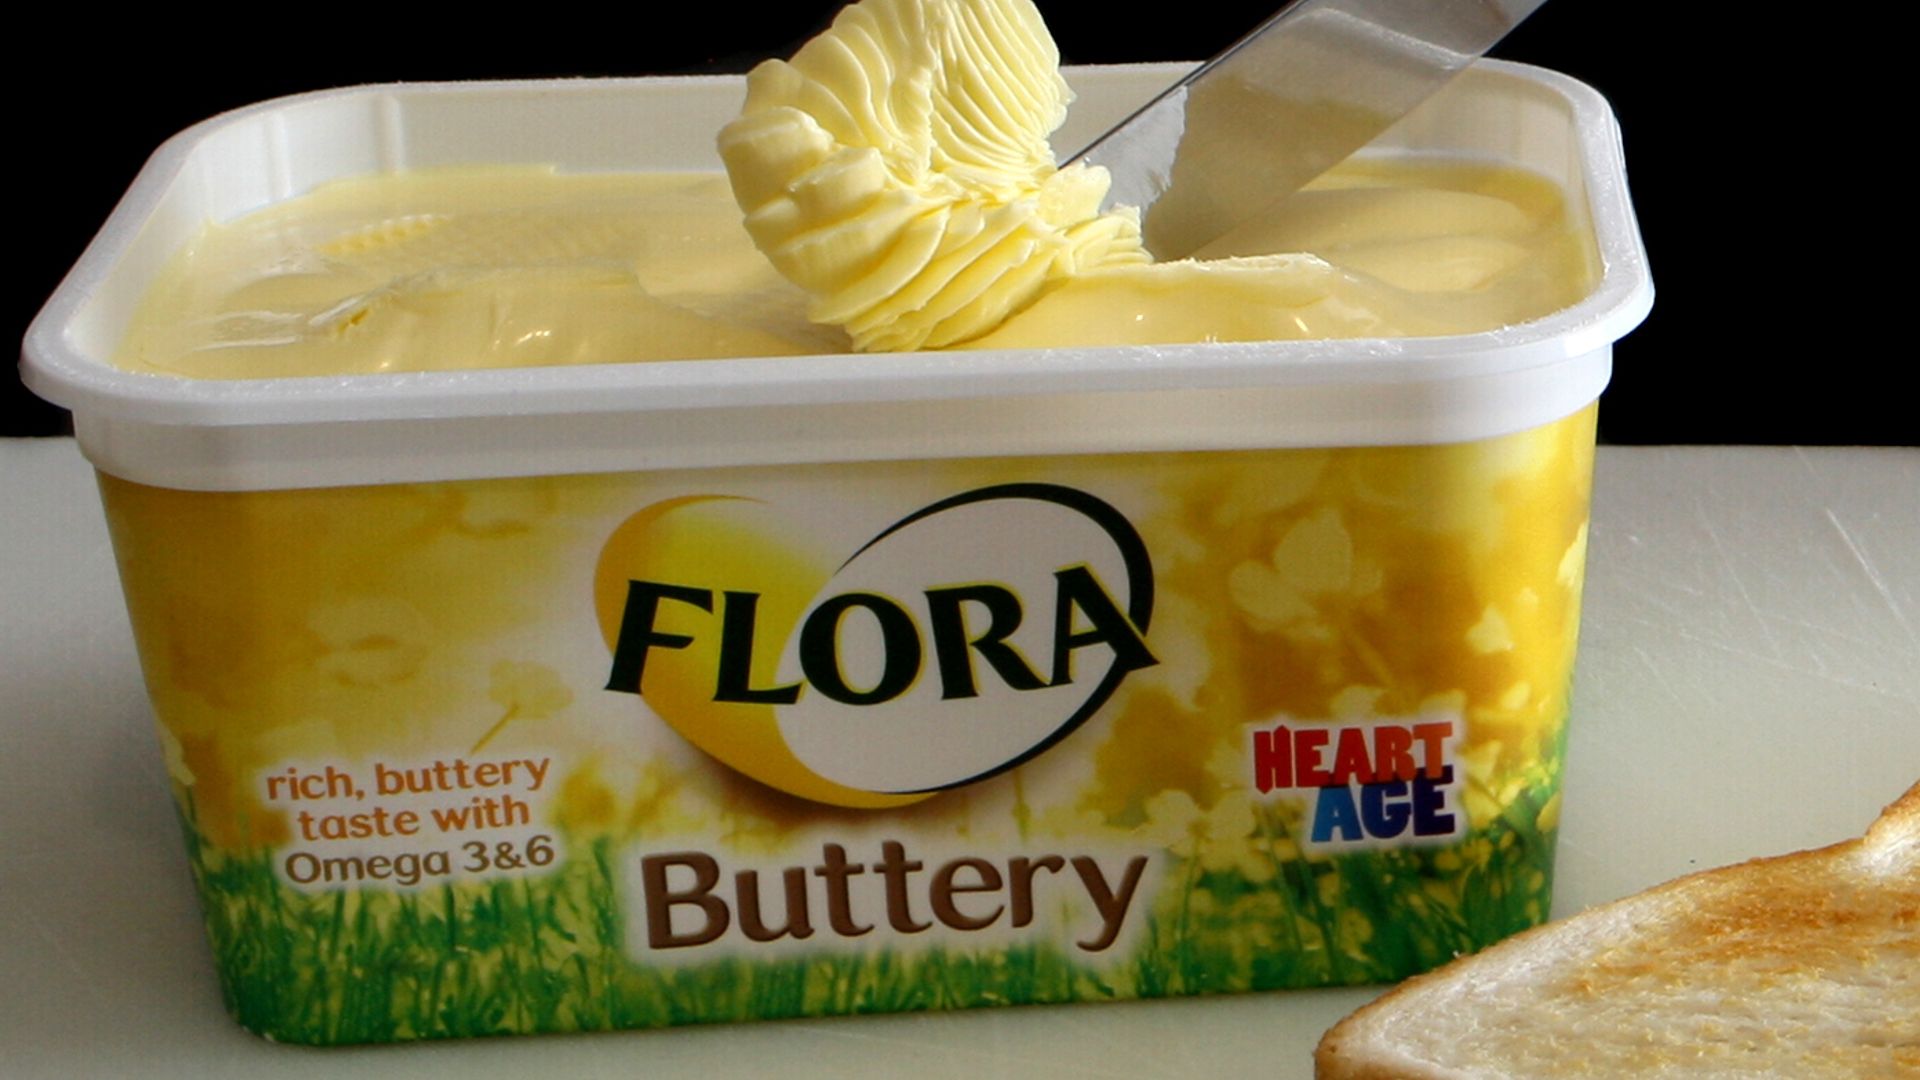
Private equity participation in large-scale fast-moving consumer goods (FMCG) carve-outs operates on a distinct set of financial and operational levers. When Apollo Global Management enters bidding for Flora Food Group—formerly Upfield, valued at approximately €7 billion—it targets a specific structural mispricing common to mature consumer asset divestitures. The valuation dynamics of Flora illustrate the mechanics of large-cap private equity buyouts, corporate unbundling strategies, and debt capacity management in high-yield credit environments.
Capital Structure and Valuation Mechanics in Mega Carve Outs
The acquisition of a global corporate spin-off at a €7 billion enterprise valuation requires balancing debt syndicated financing against sponsor equity contribution. In consumer goods carve-outs, valuation multiples typically decouple from high-growth software or specialized industrials, anchoring instead to EBITDA predictability and steady cash flow conversion.
A buyout sponsor evaluates a candidate like Flora using three primary financial parameters:
- Free Cash Flow Conversion Ratio: The percentage of EBITDA converted to unlevered free cash flow after maintenance capital expenditures and working capital adjustments. High-volume food manufacturing operations maintain predictable capital expenditure profiles, enabling debt service coverage ratios that support substantial debt loads.
- Carve-Out Operational Friction (TSA Dependency): The cost and duration of Transition Services Agreements (TSAs) required to separate parent IT systems, supply chain logistics, and shared corporate functions. Prolonged TSAs erode sponsor returns through margin drag.
- Syndicated Debt Capacity: The maximum leverage multiple obtainable in the institutional debt market without pushing credit ratings below viable yield thresholds for institutional investors.
In evaluating assets in the €5 billion to €10 billion range, sponsors model debt structures around senior secured term loans (TLB), high-yield bonds, and revolving credit facilities. When interest rates rise, leverage ratios shift downward from peak historic multiples (e.g., 6.5x-7.0x EBITDA) toward conservative bounds (4.5x-5.5x EBITDA). This reduction in leverage forces sponsors to fund a larger equity check or negotiate lower entry valuation multiples to preserve internal rate of return (IRR) targets.
The Dual Lever Playbook: Cost Rationalization vs Brand Premiumization
Sponsors execute value creation in mature consumer assets via two distinct vectors: operational cost extraction and portfolio repositioning.
Vector 1: Structural Margin Expansion
Spreads and plant-based butter categories exhibit mature growth rates in developed markets. Value creation cannot rely solely on organic revenue expansion. Private equity operators implement aggressive cost restructuring aimed at SG&A normalization:
- Footprint Rationalization: Consolidating manufacturing sites to increase plant capacity utilization rates.
- Procurement Optimization: Renegotiating raw input contracts across palm oil, canola, and packaging by aggregating regional purchasing power.
- Direct-to-Store Delivery (DSD) Optimization: Shifting distribution models away from direct-store logistics toward centralized retail warehouse routing to eliminate variable transport costs.
Vector 2: Portfolio Re-segmentation and Premiumization
Volume decline in traditional margarine categories requires active product re-segmentation. Growth within the segment shifts toward plant-based butter alternatives and specialized culinary lipids targeting higher-margin retail segments.
The strategy hinges on separating legacy brand assets from high-growth plant-based alternatives. By isolating functional channels, management can redirect capital expenditures toward consumer categories with higher pricing power and lower demand elasticity.
Exit Horizon Dynamics and Secondary Market Liquidity
Private equity entry into mega-cap consumer assets carries specific structural exit risks. A sponsor committing significant equity capital to a €7 billion asset must map viable exit pathways prior to execution:
- Strategic Sale to Global FMCG Conglomerates: Trade sales offer valuation premiums through strategic synergy realization. However, high market concentration limits the pool of prospective acquirers due to regulatory antitrust constraints.
- Initial Public Offering (IPO): Public equity markets require clear top-line revenue growth narratives alongside solid margin profiles. Pure dividend yield/cash cow narratives face variable market appetite depending on macroeconomic yield environments.
- Secondary Buyout (Sponsor-to-Sponsor): Transferring the asset to another large-cap private equity fund requires demonstrated runway for a secondary wave of operational improvement or further geographic expansion.
Portfolio Strategy Execution for Large Scale Consumer Assets
Sponsors evaluating assets in the plant-based food and spreads sector must prioritize debt service durability over aggressive top-line growth assumptions. Capital deployment requires structuring junior credit tranches to withstand raw material volatility while establishing strict timelines for TSA termination within 18 months of acquisition closing.