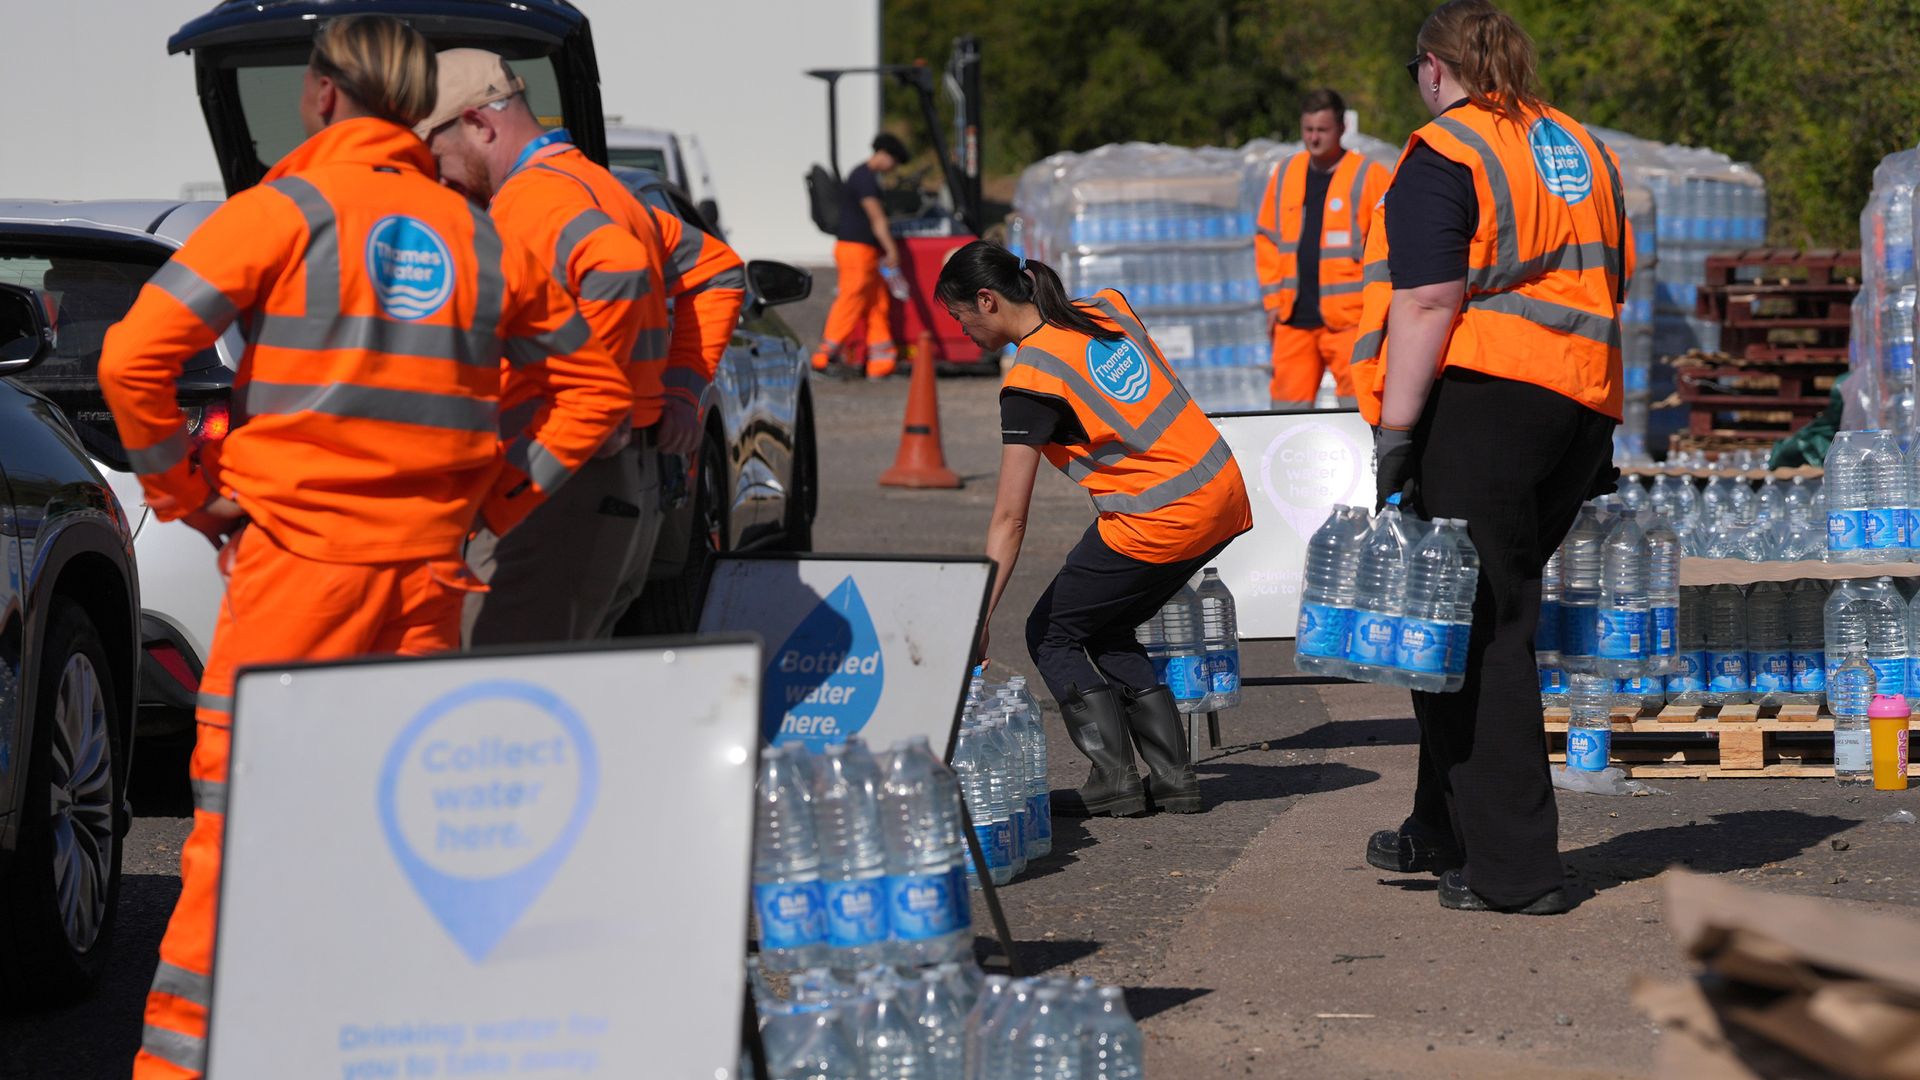
We have been fed a tidy narrative by the executives running our water networks. The warning is simple and terrifying. If credit rating agencies downgrade the sector, consumer water bills will surge by forty pounds to cover mounting debt costs.
It sounds like a threat from a mafia boss. Pay the protection money or face the consequences.
Except the entire premise is a manufactured inversion of reality.
I have watched regulated utilities play this game for decades. When performance metrics tank, when infrastructure leaks gallons of treated water into the dirt daily, and when sewage spills dominate the headlines, the boardrooms do not look inward. They look outward. They point to the financial markets and scream that investors are getting nervous. They claim that credit downgrades will force higher borrowing costs, which must inevitably fall on the domestic consumer.
Stop buying it.
A credit downgrade is not an act of God. It is a lagging indicator of operational failure and excessive leverage. For years, privatized water companies loaded their balance sheets with debt to fund massive shareholder dividends while deferring basic capital maintenance. They chose short-term cash extraction over long-term structural integrity. Now, facing the bill for their own negligence, they want to rebrand corporate mismanagement as an unavoidable market tax on ordinary households.
Let us look at the mechanics they pretend are too complex for the public to grasp. When a company borrows heavily, its credit rating reflects its ability to service that debt through operational cash flow. If a utility fails to maintain pipes, faces regulatory fines for environmental pollution, and burns cash on financial engineering, its creditworthiness drops. That is not a punishment inflicted by cruel bankers. It is an accurate audit of poor business practices.
The threat of a forty-pound bill hike assumes that consumers must eternally underwrite the cost of capital for a private monopoly that failed to manage its capital structure. That is not capitalism. That is socialism for shareholders and brutal free-market exposure for everyone else.
If a retail store runs out of inventory because the CEO spent the operating budget on luxury cars, the board fires the CEO. In the utility sector, the response is to raise prices at the register and blame Moody's.
We need to dismantle the lazy consensus that utility bills are tethered to credit ratings by some laws of physics. They are tethered to choices. Choices made by executives who prioritized debt-fueled payouts over building reservoirs and upgrading Victorian-era mains.
Imagine a scenario where a struggling utility is barred from paying dividends until leakage rates drop below benchmark levels and credit ratings recover organically through retained earnings. The outcry from the boardroom would be deafening. But the financial health of the company would stabilize without extracting a single extra penny from a family struggling to pay their monthly utility statement.
The real risk is not a credit downgrade. The real risk is allowing companies to use the credit rating system as a permanent hostage situation against regulators and consumers.
Do not let them reframe executive accountability as a consumer crisis. The forty-pound hike isn't a market necessity. It is an invoice for a broken business model, and it's time to send it back to the address on the letterhead.